October 15, 2025
Exotic Car Rental Insurance: What Credit Cards Actually Cover

By Colin Greig
Founder & Editor-in-Chief
The short answer: probably not. If you're renting a Lamborghini, Ferrari, McLaren, Rolls-Royce, or most other exotics above roughly $75,000 MSRP, most premium credit card rental programs carve exotics out of coverage, and the one major card that doesn't, the Chase Sapphire Reserve, caps coverage at $75,000, far below the value of most exotics. This isn't buried fine print that no one reads — it's stated in the benefits guides of the cards discussed in this post. Understanding where those lines fall, and what actually happens when you decline the rental company's CDW, is what this guide covers.
What's Actually Excluded (By Card)
Credit card rental car coverage works as either primary or secondary insurance on the rental vehicle for damage or theft. The coverage applies when you pay for the rental with that card and decline the rental company's Collision Damage Waiver (CDW). What the benefits guides all have in common is an "exotic" or "high-value" exclusion. Where they differ is in how they define it.
The core problem: most exotic rentals involve vehicles with an MSRP of $150,000–$500,000. The threshold that triggers exclusions is usually $75,000–$100,000 MSRP. A new Lamborghini Huracán has a base MSRP above $230,000. This isn't a borderline case — it's far outside what a standard card benefit will pay.
The $75,000 MSRP Wall
The $75,000 threshold isn't written into most card benefit guides explicitly. What the guides say instead is that they exclude "antique vehicles, exotic cars, and vehicles with an MSRP exceeding [a stated amount]" or simply "exotic and high-value vehicles." The $75,000 figure shows up in some guides as an MSRP ceiling and, for the Chase Sapphire Reserve, as the coverage cap itself; others use a qualitative "exotic" definition that the benefits administrator interprets.
In practice, any of the following models will be excluded by cards that carry an exotic or MSRP exclusion: Lamborghini (all models), Ferrari (all models), McLaren (all models), Rolls-Royce (all models), Bentley (all models), Aston Martin (all models), Porsche 911 GT3/GT3 RS, Mercedes-AMG GT R. Porsche 911 Carrera in some markets may fall under the threshold — consult your specific benefits guide.
Amex Platinum
The Amex Platinum card includes "Premium Car Rental Protection" as an add-on product you can enroll in per-rental for a flat fee (reported at $17.95–$24.95 per rental period in the US; confirm on Amex's site). This is separate from the standard secondary CDW that other cards offer — it operates as primary coverage.
What it excludes: Amex's published terms are the final word, and its products differ. The standard Car Rental Loss and Damage Insurance terms exclude exotic, high-value and limited-edition vehicles; read the Premium Car Rental Protection description of coverage for your specific rental before paying the fee.
Amex also offers Platinum Card rental car CDW as a secondary benefit for eligible rentals. The same exclusions apply.
Bottom line for Amex Platinum holders: Don't assume coverage for an exotic. Get written confirmation from Amex for the specific car before you decline the rental company's CDW.
Chase Sapphire Reserve
Chase Sapphire Reserve includes primary rental CDW as a core card benefit — no enrollment fee, no per-rental charge. It covers theft and collision damage up to $75,000, subject to exclusions.
What it excludes: Chase says the Sapphire Reserve does not exclude expensive or exotic vehicles, but it does exclude antique cars, vehicles more than 10 years old, motorcycles, and some vans. The coverage itself is capped at $75,000 for rentals of up to 31 consecutive days.
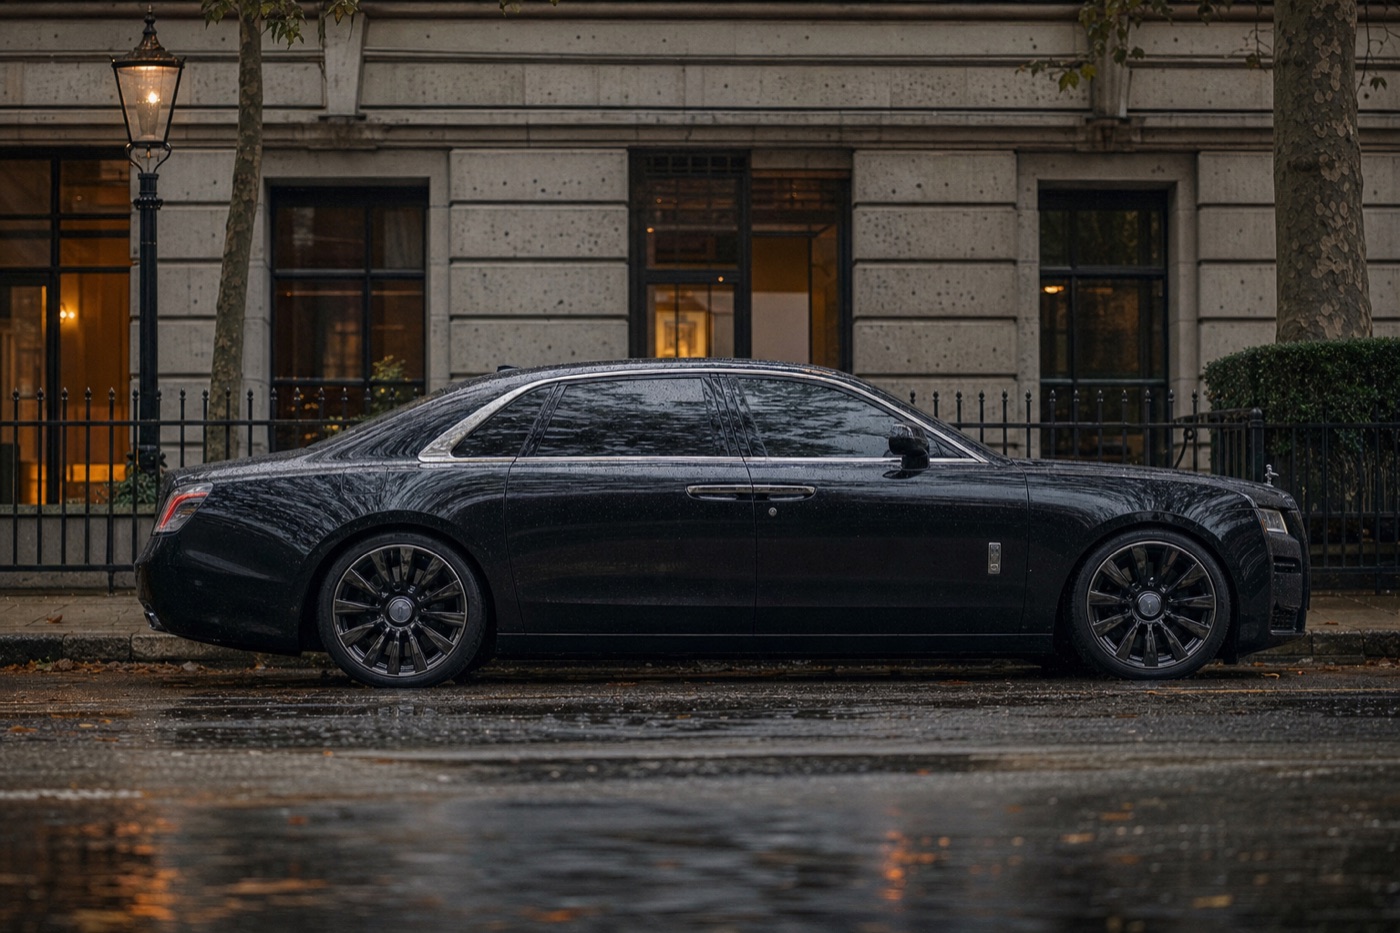
A Lamborghini Huracán, Ferrari F8, Rolls-Royce Ghost, or Porsche 911 GT3 is worth far more than $75,000, so a total-loss claim would leave a large gap, and many rental companies still require you to buy their own CDW.
What might be covered: Cars worth less than the $75,000 cap, such as a Porsche 718 Cayman, a base Corvette Stingray, or a BMW M3, are the realistic fit. Check the current benefits guide before relying on it.
Bottom line for Chase Sapphire Reserve: Primary coverage up to $75,000, which does not come close to covering a six-figure exotic. Treat it as a supplement at best, and only if the rental company accepts it.
Capital One Venture X
The Capital One Venture X includes primary rental car collision coverage as a card benefit. Capital One's help center lists expensive, exotic and antique cars among the excluded vehicles, and the card's benefits guide governs the details.
What it excludes: Capital One lists expensive, exotic and antique cars as excluded vehicles. An older Venture X guide defined "expensive" as an original MSRP above $75,000, so check the current guide for the cutoff. In practice, any vehicle from the same list above will be denied.
Bottom line for Venture X: No coverage for exotics.
Mastercard World Elite
Several cards run on the World Elite Mastercard network (including some Citi, Bank of America, and USAA products). The underlying benefit is Mastercard's Luxury Car Rental Insurance product, which follows the same guide as described above. Exclusions are consistent across World Elite issuers: exotic, antique, and high-performance vehicles as defined by the administrator are excluded.
One partial exception: some World Elite cards include a dedicated luxury vehicle benefit that provides limited liability coverage (not CDW) when renting certain higher-value vehicles from participating luxury programs like Hertz Dream Cars. These programs rarely include Lamborghini or Ferrari — they typically cover Mercedes S-Class, BMW 7 Series, and similar. Don't confuse this with collision coverage.
What Rental Companies Actually Require
Rental companies have their own requirements that exist independently of what your credit card covers. Most exotic rental companies in the US require one of:
- Purchase of their CDW (typically $100–$300/day, often with a residual deductible of $2,500–$10,000)
- Proof of standalone insurance that explicitly covers the rented vehicle (including the specific make and model) with liability and collision coverage up to the vehicle's value
- A deposit hold large enough to cover the full vehicle value in the event of loss
Most operators strongly prefer option 1 — their own CDW — because it's clean and they control the claims process. Some operators require it with no alternative. Read the terms before you book.
Primary vs Secondary Coverage
On eligible (non-exotic) rental cars, the distinction between primary and secondary credit card coverage matters practically:
Primary coverage (Sapphire Reserve, Venture X, Amex Premium add-on) pays first, before your personal auto insurance. This means no claim goes through your personal insurer, your premiums aren't affected, and you don't pay a personal deductible.
Secondary coverage (standard Visa Signature, older cards) only kicks in after your personal auto insurance pays. This means filing a personal insurance claim, potentially affecting your rates, and having both deductibles count.
For exotics, this distinction is moot — neither applies. But if you're renting a sub-$75,000 performance car (Corvette, BMW M cars, base Porsche models), the primary vs. secondary distinction is worth understanding.
What to Do Instead
If you're renting an exotic, you have three real options:
1. Buy the rental company's CDW. It's expensive — $100–$300/day — and often has a residual deductible. But it's clean and the operator knows what to do with it. For a 2-day Huracán rental, budgeting $300–$600 for CDW is part of the real cost.
2. Specialty rental insurance. Companies like Bonzah, Insure My Rental Car, and Exotic Car Insurance (a specialist broker) offer per-rental policies that cover exotic vehicles. Pricing varies widely by vehicle value and rental period — budget $50–$150/day for a comprehensive standalone policy on a six-figure car. Read the exclusions carefully; some of these policies have their own MSRP caps.
3. Standalone personal umbrella or collector car policy. If you rent exotics regularly (more than 3–4 times per year), a non-owner exotic rental endorsement or collector car policy rider may be the most cost-effective solution. These policies are niche; an independent broker who specializes in collector and exotic vehicle coverage (not a standard auto insurance agent) is the right place to start.
What doesn't work: Calling your personal auto insurer and assuming your policy extends to exotics. Standard personal auto policies exclude vehicles not listed on the policy, and many have specific exotic car carve-outs. Some policies extend to rental cars generally — check your declarations page — but this coverage almost never applies to vehicles outside the standard market value range your insurer typically covers.
Browse our directory of exotic rental companies to find operators who can clarify their insurance requirements before you book.
Frequently Asked Questions About Credit Card Insurance for Exotic Car Rentals
Does my credit card cover damage to a rented exotic car?
Almost certainly not in full. Many premium cards, such as the Capital One Venture X, exclude exotic and high-value vehicles outright. The Chase Sapphire Reserve doesn't exclude them but caps coverage at $75,000, well below the base price of a Lamborghini Huracán, which is above $230,000.
What MSRP threshold triggers the exotic car exclusion?
It depends on the card. Some set an original MSRP cutoff (Capital One's older Venture X guide used $75,000), some list excluded brands, and the Chase Sapphire Reserve has no MSRP exclusion but a $75,000 coverage cap. Every Lamborghini, Ferrari, McLaren, Rolls-Royce, Bentley, and Aston Martin model exceeds those figures. Check your specific benefits guide.
Does the Amex Platinum Premium Car Rental Protection cover a Lamborghini?
Don't count on it. The Amex Premium Car Rental Protection add-on (reported at $17.95–$24.95 per rental period in the US; confirm on Amex's site) is no guarantee for a Lamborghini or Ferrari, and Amex's other rental insurance terms exclude exotic and high-value vehicles. Get written confirmation from Amex for the specific car.
Does Chase Sapphire Reserve cover exotic car rentals?
Only up to $75,000. Chase says the Sapphire Reserve covers rentals up to $75,000 and does not exclude expensive or exotic vehicles, but that cap falls far short of the value of a Lamborghini, Ferrari, or Rolls-Royce, and many exotic rental companies require their own CDW regardless.
What insurance should I get when renting an exotic car?
The rental company’s Collision Damage Waiver (CDW) is the standard option and is often mandatory for exotic tiers — some operators build it into the quoted rate. A few specialty travel insurance providers offer standalone exotic car rental coverage. Compare the deductible and coverage cap carefully before assuming the CDW alone is sufficient.